
Chapter 3: Asset Managers: The ETF Is Only the Front Door
The question this chapter answers: Why did BlackRock, Fidelity and Vanguard go from opposing crypto ETFs to issuing and distributing them? What money are they actually making?
If you work at a wealth manager, broker or asset manager and are deciding whether to launch crypto products, this chapter wants to help you work out just one sum: if crypto ETFs themselves make almost no money, what exactly are the giants fighting over?
The Fastest ETF in History, a Rounding Error in BlackRock’s Revenue
In October 2017, BlackRock chairman and CEO Larry Fink called bitcoin an “index of money laundering.”
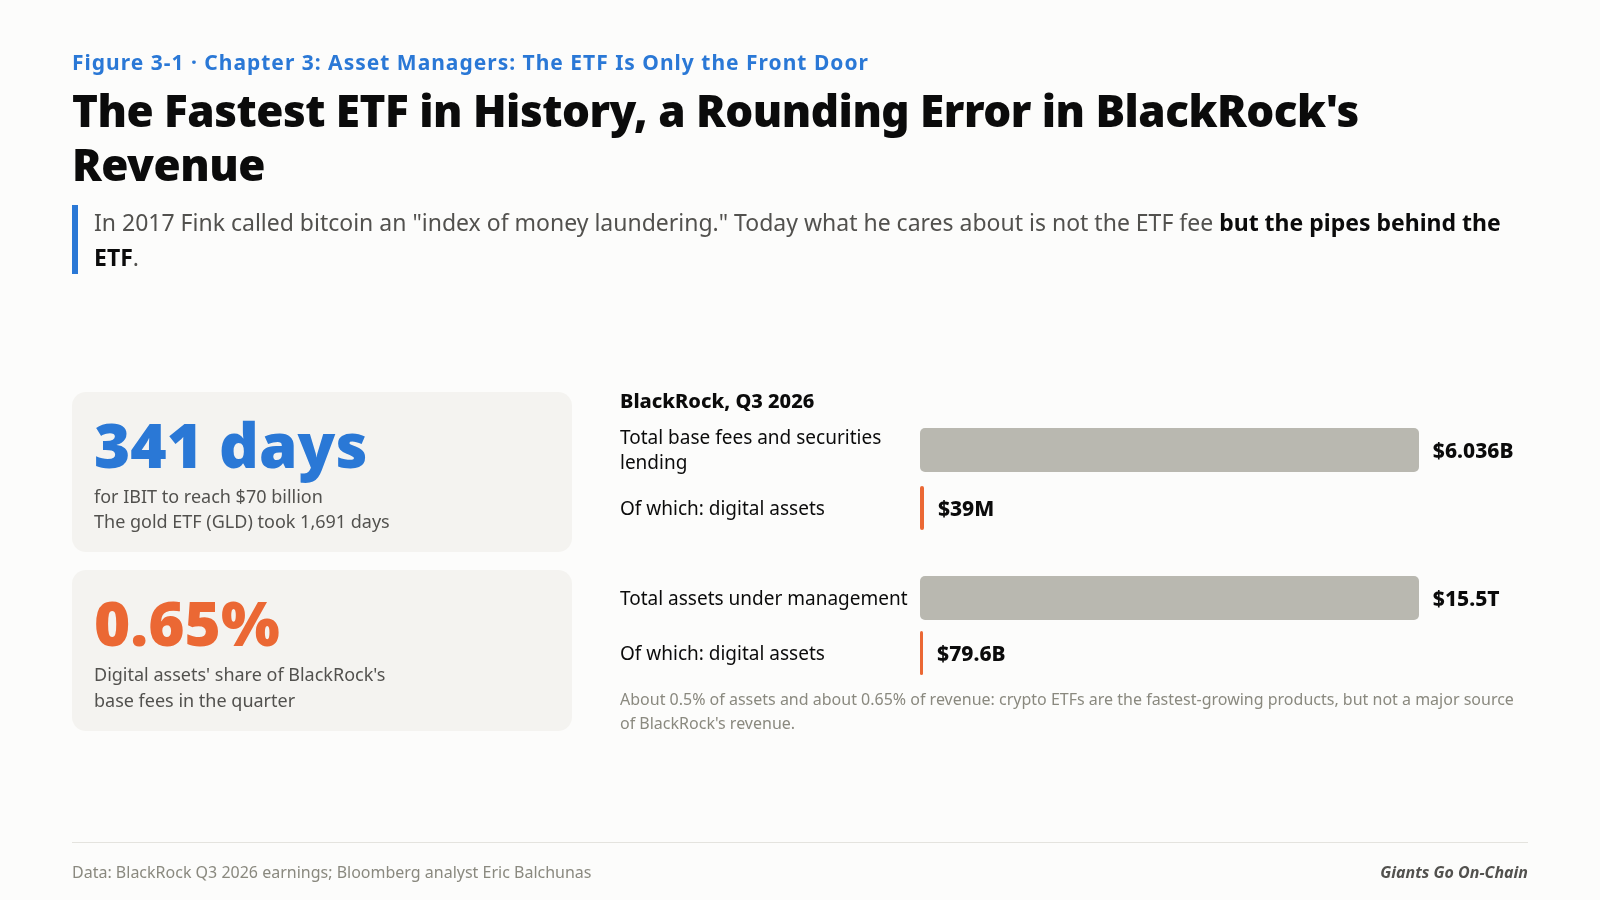
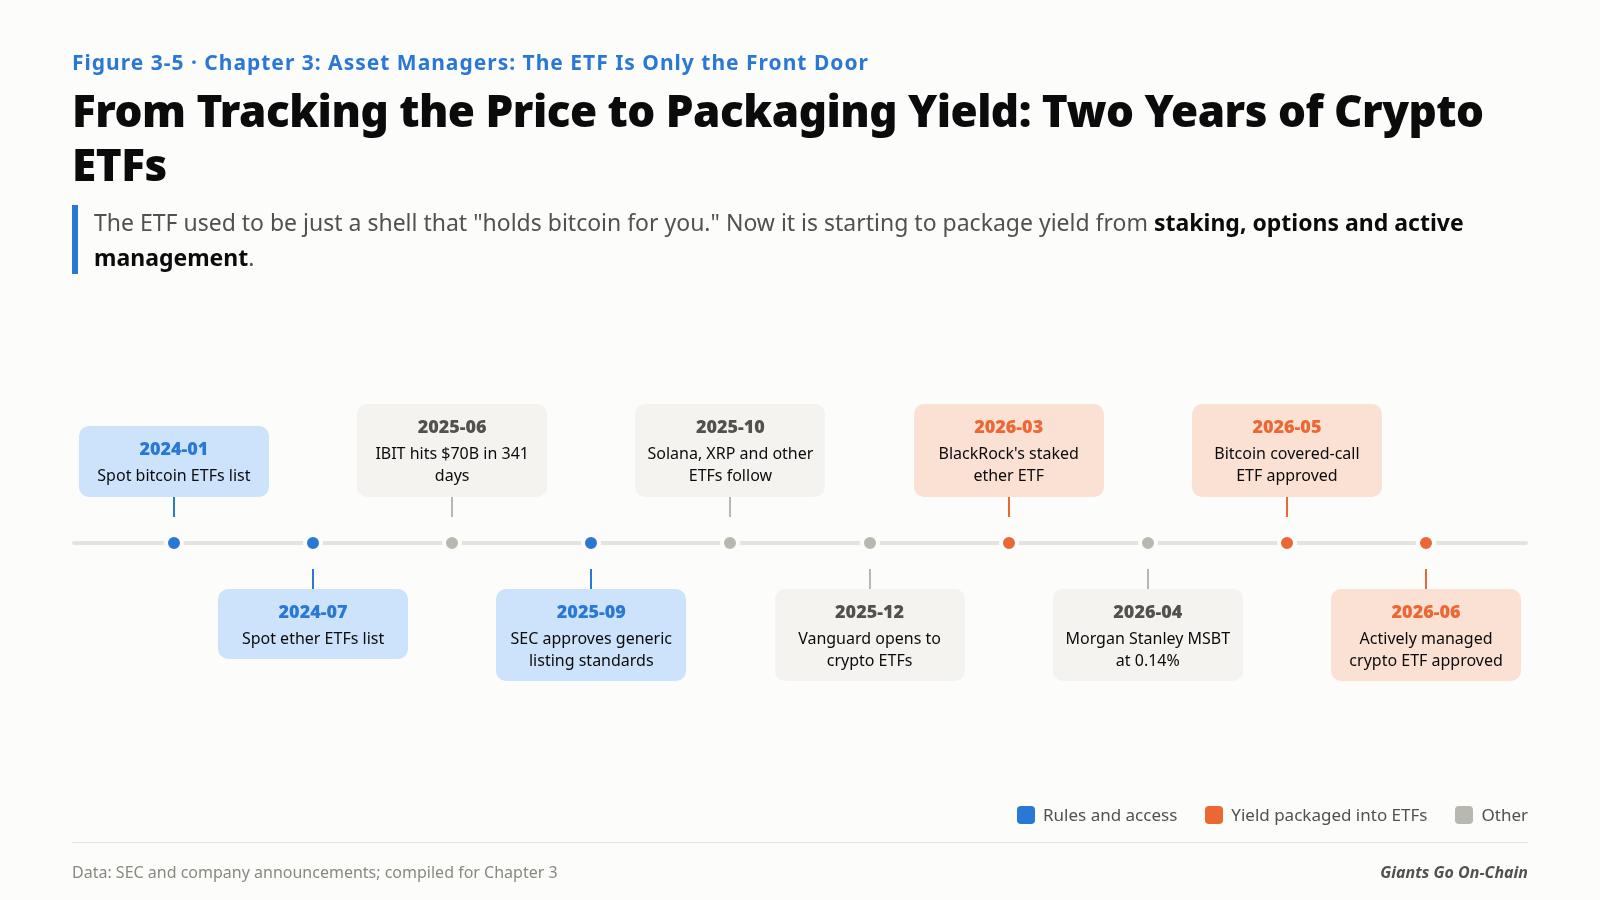
Seven years later, BlackRock’s spot bitcoin ETF (ticker IBIT) listed in January 2024 and reached $70 billion in assets in just 341 days. The previous record belonged to State Street’s gold ETF (GLD), which took 1,691 days. For a time IBIT was bigger than BlackRock’s own gold fund, making it the largest of the firm’s more than 1,400 funds worldwide.
Now look at BlackRock’s results for the third quarter of 2026. As of September 30, its digital asset products held about $79.6 billion, and they brought in $39 million of base management fees that quarter. In the same quarter, BlackRock’s total base fees and securities lending revenue came to $6.036 billion. Digital assets were just 0.65%.
The fastest-growing ETF in history contributed less than 1% of the revenue of the world’s largest asset manager.
Fink has not got his numbers wrong. In his annual letter to shareholders this March, he wrote: “Tokenization today is roughly where the internet was in 1996.” What he cares about is not the management fee at the ETF layer but the pipes behind the ETF. The ETF is the front door, not the business itself.
Post-mortem: Why Grayscale Couldn’t Hold On
To understand why the giants don’t care about ETF management fees, start with a pioneer that couldn’t hold its ground: Grayscale.
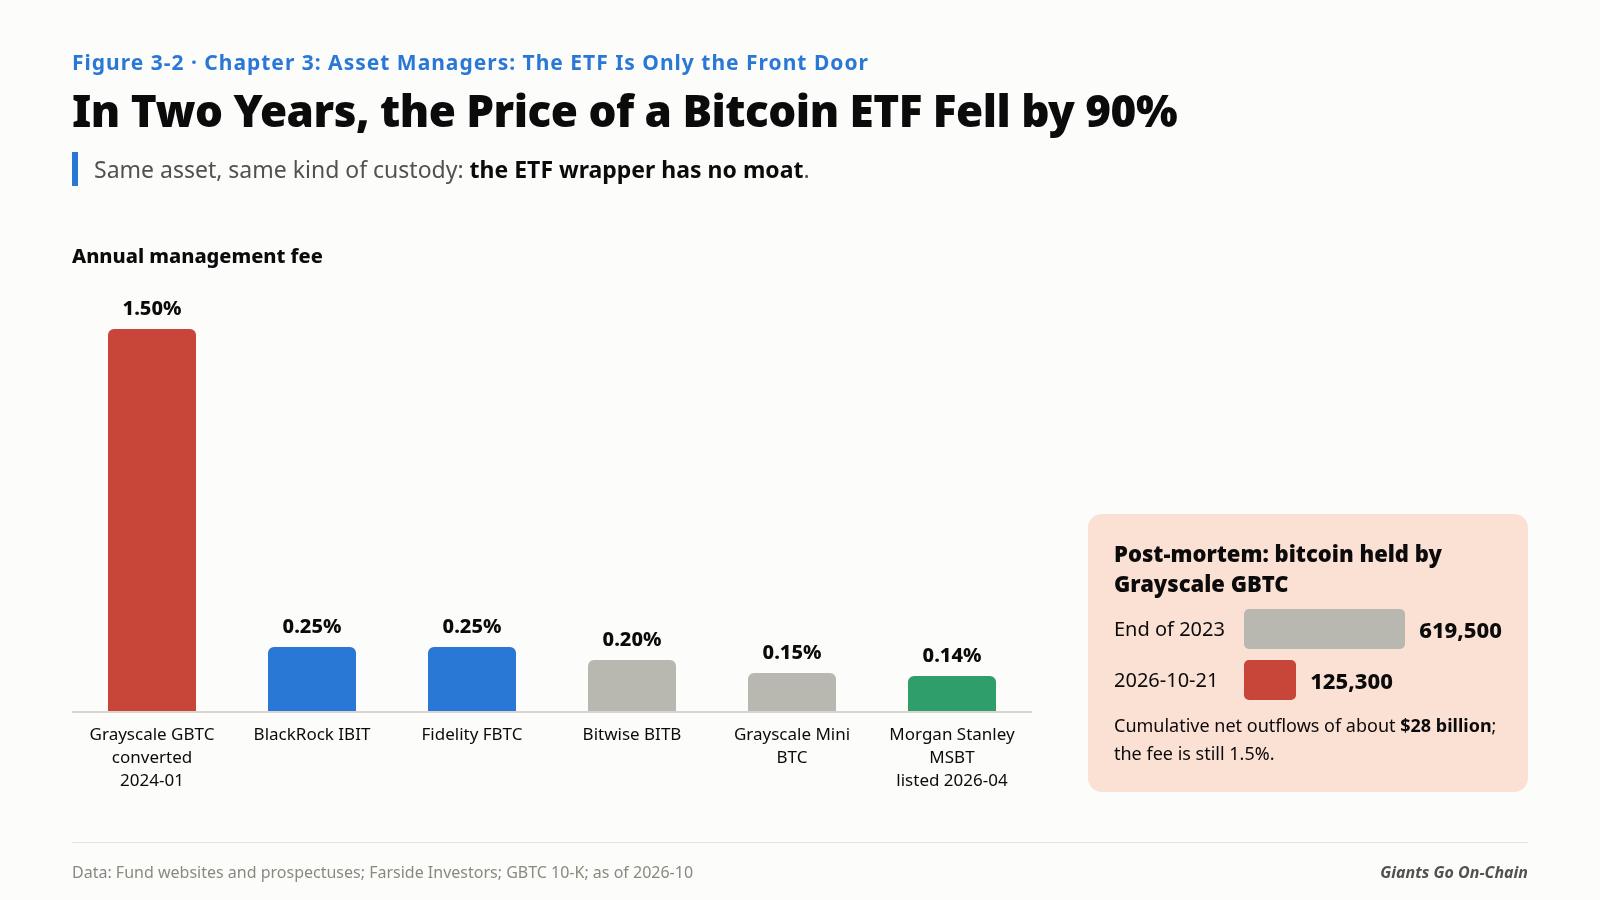
Before January 11, 2024, the Grayscale Bitcoin Trust (GBTC) was almost the only way for American investors to buy bitcoin in a brokerage account. It could not be redeemed, it traded at a persistent premium or discount, and it charged a management fee of 1.5% a year. At the end of 2023 it held about 619,500 bitcoin.
After the conversion to ETFs, the same bitcoin cost just 0.25% in IBIT and in Fidelity’s FBTC. As of October 30, 2026, GBTC had seen cumulative net outflows of about $28 billion; by late October it held only about 125,000 bitcoin, 80% less than before the conversion. Its fee is still 1.5% today.
The failure had three layers:
- The product is a commodity. Every spot bitcoin ETF holds the same asset, most use Coinbase as custodian, and the indices they track are much the same. Investors can see that, and there is no reason to pay six times as much for the same thing.
- Prices only go one way: down. On April 8, 2026, Morgan Stanley launched its own bitcoin ETF (MSBT) with a fee of 0.14%, currently the lowest of any. From 1.5% to 0.25% to 0.14%: in two years, the price of a bitcoin ETF has been cut by 90%.
- The barrier to entry is gone. On September 17, 2025, the SEC approved the exchanges’ “generic listing standards”: qualifying crypto commodity ETFs no longer need approval one by one. ETFs on Solana, XRP and other coins followed quickly, and 2026 brought actively managed crypto ETFs.
So the ETF wrapper has no moat. Grayscale, which lived on the wrapper alone, couldn’t hold on, and BlackRock doesn’t live on the wrapper.
The Asset Manager’s Three Revenue Streams
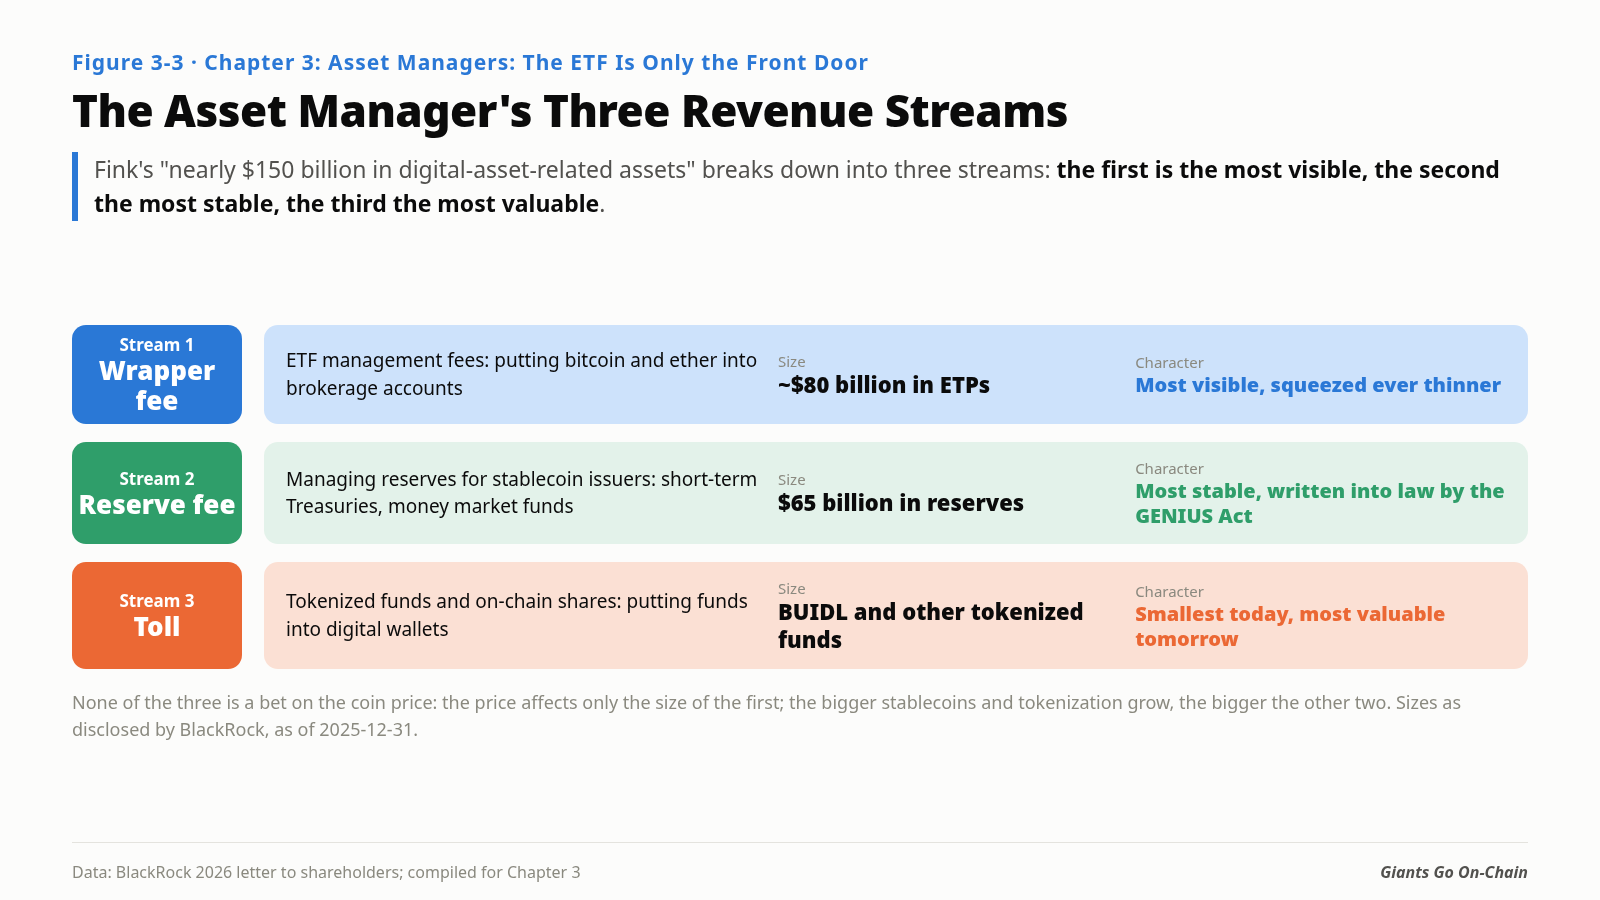
The money BlackRock can make from crypto falls into three streams. I call them “the Asset Manager’s Three Revenue Streams”:
The first stream: the wrapper fee. This is the ETF management fee. IBIT holds about $67 billion; at 0.25%, that is about $170 million a year. This money is visible, but the fee war keeps squeezing it thinner.
The second stream: the reserve fee. Stablecoin issuers have to put their reserves into short-term Treasuries and money market funds, and someone has to manage that money. Fink disclosed in his letter that, as of the end of 2025, BlackRock managed $65 billion in stablecoin reserves, the largest piece being the reserve fund Circle set up for USDC. In other words, for every extra dollar of stablecoins issued, BlackRock manages one more dollar. The GENIUS Act, covered in Chapter 1, says reserves may only be held in cash, short-term Treasuries and related money market funds, which effectively writes this stream into law.
The third stream: the toll. This is income from tokenized funds and on-chain fund shares. The most representative example is BlackRock’s tokenized money market fund BUIDL, which Chapter 4 covers in detail. This stream is the smallest today, but Fink’s vision for it is the biggest: “Half the world’s people have a digital wallet on their phone. Imagine if that same wallet let you invest in a basket of companies as easily as making a payment.” Whoever’s funds get into the wallet collects the toll.
Add the three together and you get what Fink called “nearly $150 billion in digital-asset-related assets”: about $80 billion in ETFs, plus $65 billion in stablecoin reserves, plus tokenized funds. The first stream is the most visible, the second the most stable, and the third the most valuable.
The three streams have one thing in common: none of them is a bet on the coin price. Bitcoin’s rises and falls affect only the size of the first stream; the other two grow as stablecoins and tokenization grow. For BlackRock, crypto is not an investment but a new channel for distributing assets.
Three Giants, Three Postures
The asset management giants beyond BlackRock have come in in completely different ways.
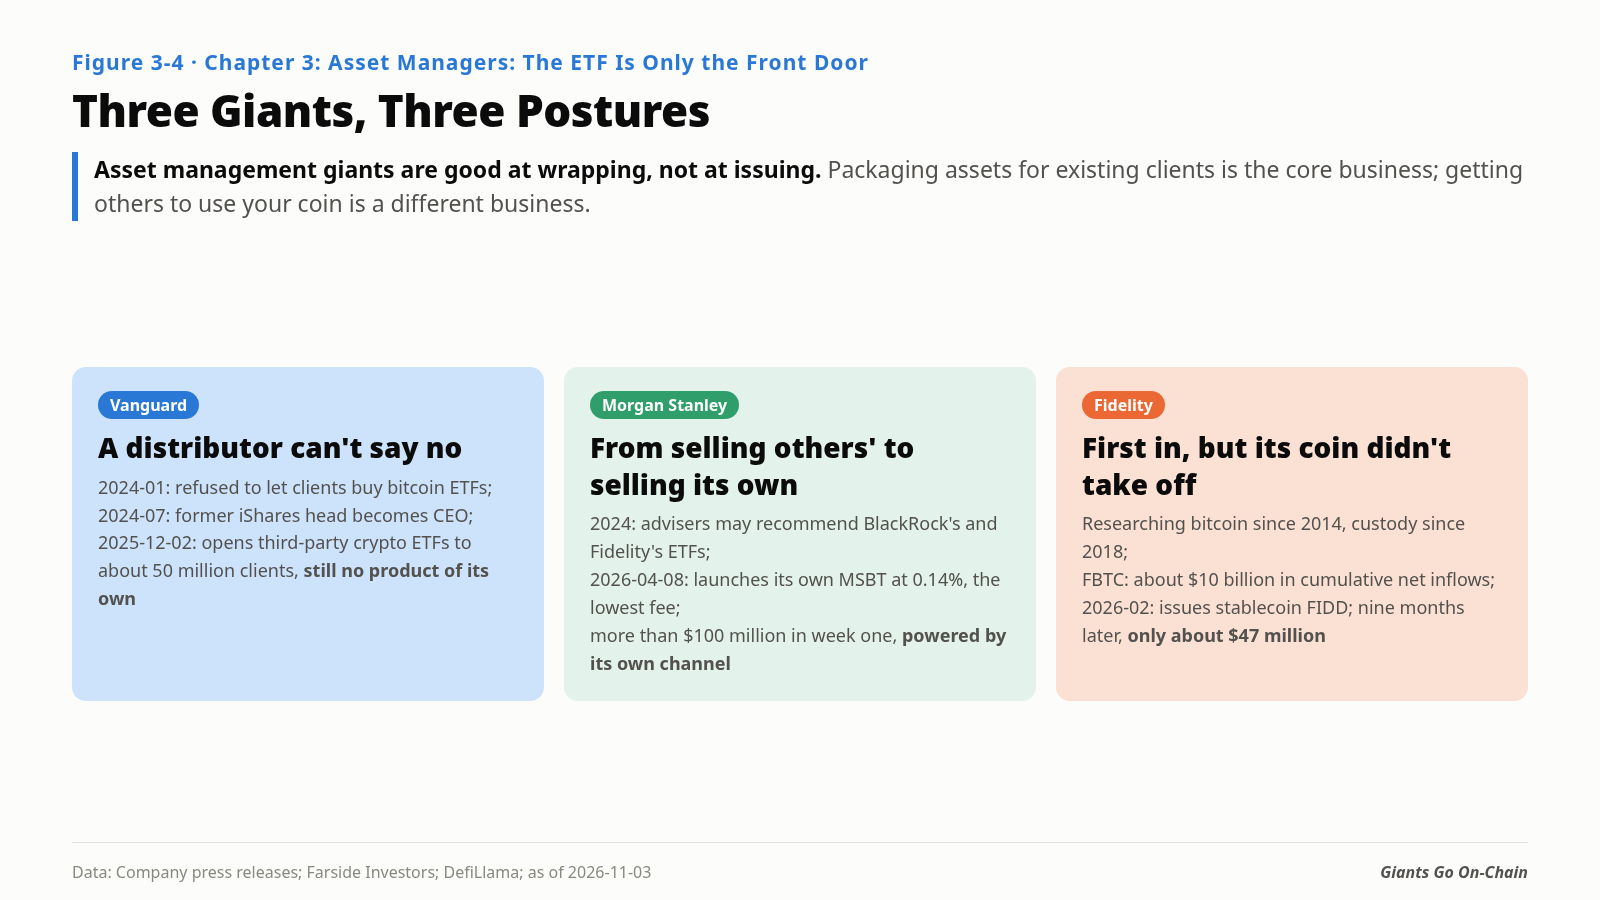
Vanguard: a distributor can’t say no. When spot bitcoin ETFs listed in January 2024, Vanguard was the only major brokerage that refused to let clients buy them on its platform, arguing that crypto did not fit its “long-term, low-cost” investment philosophy. Some clients and advisers moved to Fidelity and Schwab. In July 2024, Salim Ramji, who had run iShares at BlackRock, became Vanguard’s CEO. On December 2, 2025, Vanguard opened trading in third-party crypto ETFs and mutual funds to about 50 million clients, but to this day it has not launched a crypto product of its own.
This is the textbook choice for a distributor: you can choose not to make the product, but you can’t stand in your clients’ way. If clients can buy something elsewhere and you won’t let them, they will leave and take their other assets with them.
Morgan Stanley: from selling others’ products to selling its own. In 2024, Morgan Stanley let its financial advisers recommend bitcoin ETFs to eligible clients; the products were BlackRock’s and Fidelity’s. In April 2026 it launched its own MSBT, becoming the first U.S. bank-affiliated asset manager to issue a crypto ETF. It pulled in more than $100 million in its first week, the most successful ETF launch in the firm’s history. What lets it cut the fee to 0.14% is its own adviser network and trillions of dollars in client assets. It is Grayscale’s mirror image: whoever owns the distribution channel can sell the wrapper at the lowest price.
Fidelity: first in, but its coin didn’t take off. Fidelity began researching bitcoin in 2014 and set up a custody subsidiary in 2018. Its spot ETF, FBTC, has drawn about $10 billion in cumulative net inflows, the largest after IBIT. In February 2026, through its newly obtained national trust charter, it issued its own stablecoin, Fidelity Digital Dollar (FIDD). Nine months later, FIDD’s circulating supply was only about $47 million, less than 0.02% of all stablecoins.
Fidelity’s experience shows one thing: asset management giants are good at wrapping, not at issuing. Packaging bitcoin into an ETF and selling it to existing clients is an asset manager’s core business; issuing a stablecoin requires exchanges, wallets and merchants willing to accept it, which is a different business entirely. Chapter 2 said that “regulators can issue licenses, but they can’t create demand,” and the same holds for the asset management giants.
ETFs Are Becoming Yield Products
The first bitcoin ETFs did one thing: track the price. Now ETFs are starting to package on-chain yield.
On March 12, 2026, BlackRock launched a staked Ethereum ETF (ETHB), with 70% to 95% of its ether staked and the staking rewards paid out to investors monthly. In May, the SEC approved BlackRock’s bitcoin covered-call income ETF. In June, T. Rowe Price’s actively managed crypto ETF was approved.
The role of the ETF is changing. It used to be just a shell that “holds bitcoin for you”; now it is starting to package on-chain interest, staking rewards and options income into products that traditional accounts can buy.
For the asset management giants, this is the road from the first stream to the third: use the ETF to bring in clients and regulators first, then put more and more on-chain things into the same shell.
Demand doesn’t always grow. In 2026 so far, U.S. spot bitcoin ETFs have had net outflows on almost half of all trading days, and the bitcoin price is about 40% below its October 2025 high. Yet as of October 30, these ETFs still had about $57 billion in cumulative net inflows and about $104 billion in total assets. Money flows out when prices fall, but the wrapper, once built, doesn’t get torn down.
If You’re Making the Call
If you are responsible for crypto products at a wealth manager, broker or asset manager, ask three questions first:
- Which stream of money are you earning? If you are only launching an ETF to collect management fees, you are competing with 0.14%, and unless you have your own distribution like Morgan Stanley, it is hard to win.
- Can your clients buy it elsewhere? If they can, open the channel first, as Vanguard did. The cost of turning clients away is far higher than the risk of listing a third-party product.
- Do you have the capabilities to capture the second and third streams? Stablecoin reserve management, tokenized fund shares, on-chain custody: these are the businesses after the ETF. If you lack them, find custody and issuance partners first rather than rushing to issue your own coin.
In one sentence: asset management giants are not selling bitcoin, they are selling the wrapper; the wrapper will keep getting cheaper, and what is really valuable is the pipe behind it.
Data and Sources (as of 2026-11-03)
Verified:
- BlackRock Q3 2026 digital asset AUM of $79.632 billion, quarterly net inflows of $7.907 billion, base fees and securities lending revenue of $39 million; total base fees and securities lending revenue of $6.036 billion: BlackRock Q3 2026 earnings release (SEC EX-99.1)
- Fink’s 2026 letter to shareholders (tokenization roughly where the internet was in 1996; $65 billion in stablecoin reserves, nearly $80 billion in digital asset ETPs, nearly $150 billion in related assets, as of 2025-12-31; the digital wallet passage): BlackRock annual chairman’s letter, The Block
- IBIT reached $70 billion in 341 days; GLD took 1,691 days: Yahoo Finance/Fortune
- IBIT holdings worth about $67 billion: Morningstar
- Cumulative net inflows into spot bitcoin ETFs (IBIT $66.31 billion, FBTC $10.18 billion, GBTC −$28.05 billion, total $57.05 billion, through 2026-10-30): Farside Investors; total assets of about $104.3 billion, net outflows on 48% of trading days in 2026: Simple Mining
- GBTC held 619,525.93 bitcoin at the end of 2023: GBTC 10-K; held 125,264.91 bitcoin on 2026-10-21, fee of 1.50%: Grayscale
- MSBT listed 2026-04-08, fee of 0.14%, first issuance by a bank-affiliated asset manager: Morgan Stanley press release, FinTech Weekly; more than $100 million in the first week: CoinDesk
- SEC approved generic listing standards on 2025-09-17: SEC statement by Commissioner Peirce; approval of T. Rowe Price’s active crypto ETF (2026-06-12) and the iShares bitcoin covered-call income ETF (2026-05-29): SEC list of orders
- Vanguard opened its platform to third-party crypto ETFs on 2025-12-02, about 50 million clients, no proprietary products: CoinDesk, Vanguard website
- ETHB listed 2026-03-12, 70%–95% staked: CoinDesk, Yahoo Finance
- FIDD issued 2026-02-04 by Fidelity Digital Assets, N.A.: Fidelity press release; circulating supply of about $46.83 million: DefiLlama API (retrieved 2026-11-03)
- Bitcoin price of $77,033: CoinGecko API (retrieved 2026-11-03)